Tennessee Lawmakers Open Medical Marijuana Hearings as TBI Pushes Back
Legislators began medical marijuana hearings, and a Tennessee Bureau of Investigation representative opened the record by calling the plant a 'dangerous drug.'
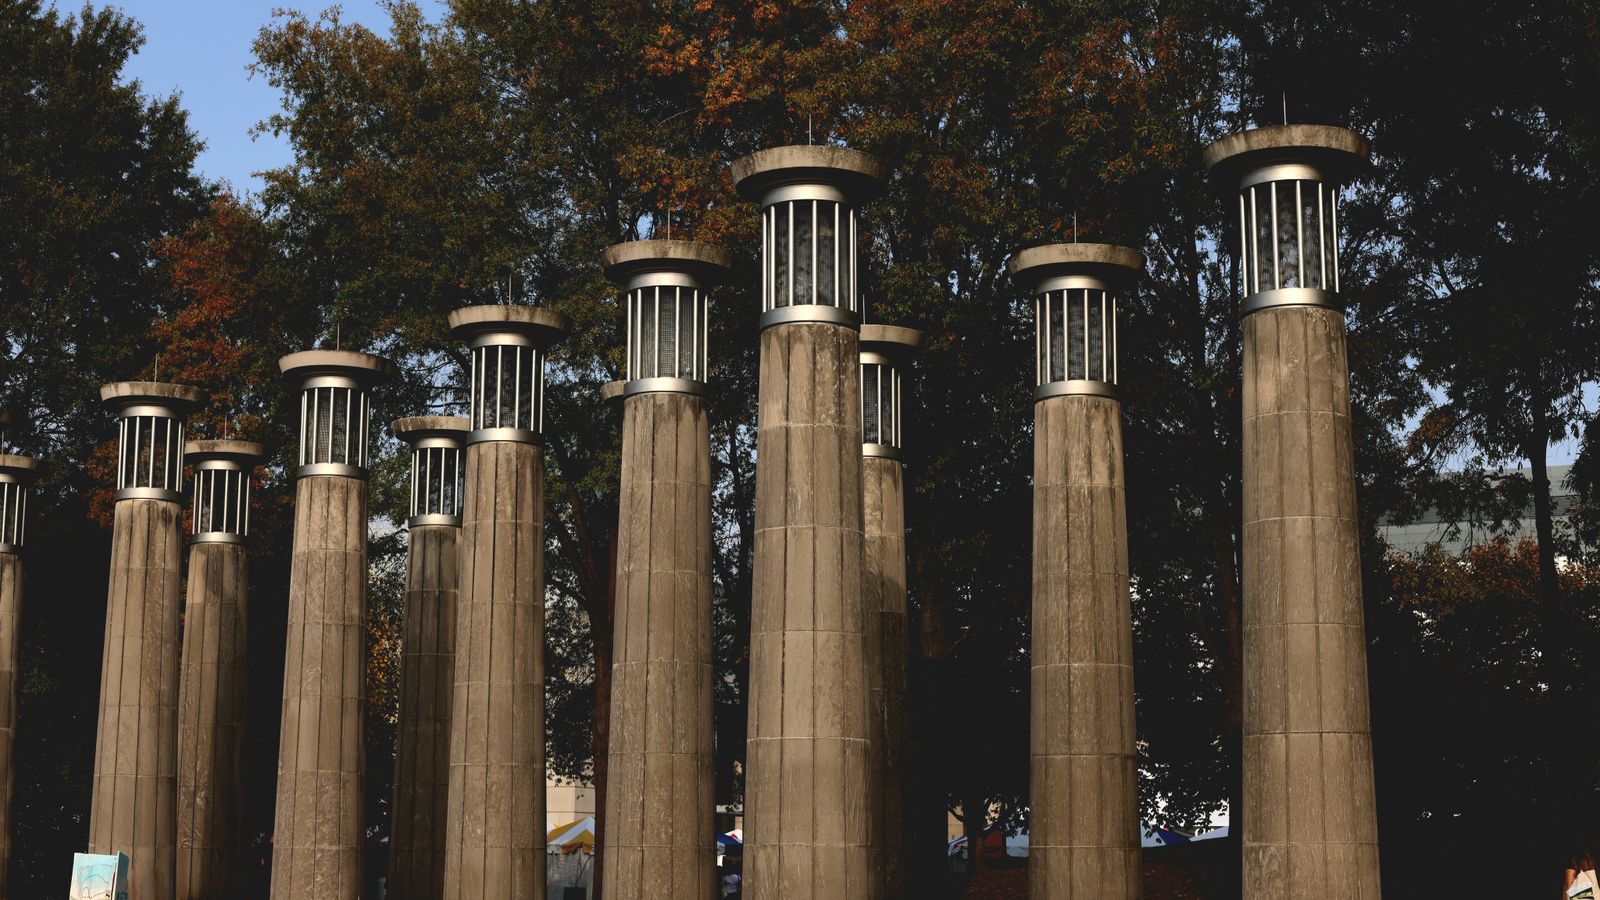
Row of bell carillons at Bicentennial Capitol Mall in Nashville, Tennessee.
Hearings open with law enforcement on record
Tennessee legislators started formal medical marijuana hearings, and the first notable testimony came from law enforcement, not patients or operators.
The Chattanooga Times Free Press reported the hearings on Oct. 6, 2026. Its headline said a representative of the Tennessee Bureau of Investigation called marijuana a 'dangerous drug.' CannIntel had only the published headline and summary when this report was written, so the account below is limited to what that source supports.
Here the stakes are structural. Tennessee has no comprehensive medical cannabis market, so whatever framework emerges would decide who holds a license, how revenue is taxed and whether operators inherit the federal tax penalty under 280E.
What the TBI position signals
A state investigative agency opposing medical marijuana in the first hearing suggests any bill will be drafted around enforcement concerns.
That's not a surprise, since agencies that police controlled substances rarely volunteer to endorse a legal market, and the TBI's role makes its view relevant to licensing, background checks and diversion controls.
Still, one agency's characterization isn't a vote count. Hearings are where positions get recorded, not where bills are decided.
What the signal doesn't tell us
The headline doesn't identify the committee, the bill number, the TBI witness or any proposed licensing or tax terms.
Those gaps matter for compliance planning. Without statutory text, no one can say whether the legislature is weighing a narrow patient-access measure, a vertically integrated license model or a study committee.
CannIntel will update this report when the hearing record and any bill text are available.
The 280E problem, read literally
On a strict reading, IRC §280E turns on federal drug schedule status, not on whether a state has legalized the activity.
The statute bars deductions and credits for any trade or business that consists of trafficking in controlled substances 'within the meaning of schedule I and II' of the Controlled Substances Act. State authorization doesn't change that text. A Tennessee licensee selling marijuana would be tested against the federal schedule in force for the tax year, so a change in federal scheduling would change the analysis. A state program alone wouldn't.
For operators, that means cost of goods sold becomes the main lever, and the state's license structure will influence what qualifies as inventory cost. The math is brutal when a business can't deduct rent, payroll or marketing outside COGS.
Where Tennessee's tax code would intersect
Tennessee's business taxes, the franchise and excise taxes under Title 67, would reach licensed cannabis businesses regardless of the personal income tax picture.
Wages go untaxed in Tennessee, but the state levies an excise tax of 6.5% on net earnings and a franchise tax measured by net worth or property. The excise base generally starts from federal taxable income. On a strict reading, a 280E disallowance at the federal level would therefore flow into the state calculation unless the legislature writes a decoupling provision.
Decoupling is the question to watch. Several legalizing states have addressed it by statute, and the choice can be worth more to operators than the license fee itself.
Neighbors set the competitive context
Tennessee borders states that already authorize medical cannabis, including Kentucky, Arkansas, Missouri and Mississippi, which sharpens the cross-border revenue argument.
Lawmakers in states without programs often hear that patients cross state lines to buy elsewhere. Whether that argument carries weight in Tennessee will depend on testimony that hasn't yet been reported in detail. Supporters would need data. Opponents have already supplied a frame.
For full background on this story, see the CannIntel topic hub on Tennessee medical marijuana legislation.
What operators and investors should track
Until bill text appears, the actionable signals are the hearing schedule, any sponsor's draft and whether revenue officials are asked to testify.
A fiscal note from the state would show how lawmakers expect to tax the product and whether they've considered 280E. THC potency caps, DEA scheduling developments and any banking provisions would also shape the economics.
Watch for the committee's next hearing date, and for whether a bill with specific license and tax language gets filed before the session opens.
Frequently asked questions
What happened in Tennessee's medical marijuana hearings?
According to the Chattanooga Times Free Press, Tennessee lawmakers began hearings on medical marijuana, and a Tennessee Bureau of Investigation representative called the drug 'dangerous.' The headline doesn't identify the committee, the bill or the witness, and CannIntel will update as the hearing record becomes available.
Does Tennessee have a medical marijuana program?
Tennessee doesn't have a comprehensive medical cannabis market. The hearings are the legislature's latest look at whether to create one. No bill text, license structure or tax rate has been reported in the source CannIntel reviewed.
How would IRC §280E affect Tennessee operators?
Section 280E bars deductions for businesses trafficking in Schedule I or II substances. On a strict reading, it applies based on federal scheduling regardless of state law, so Tennessee licensees would be limited largely to cost of goods sold deductions unless federal scheduling changes.
How does Tennessee tax business income?
Tennessee levies a 6.5% excise tax on net earnings and a franchise tax, both under Title 67. The excise base generally starts from federal taxable income, so a 280E disallowance could carry into state returns unless the legislature adopts a decoupling provision.
Sources
The cannabis newsletter you forward to your team.
Federal policy, market data, grower alerts, and the one story that matters today. Sent every weekday at 7am. Free.
No spam. Unsubscribe with one click. 21+ only.
Related from Laws
Talking Joints Memo Revisits Portugal's 25 Years of Decriminalization
A 25-year retrospective on Portugal's 2001 drug law lands weeks before the US federal hemp redefinition, sharpening the gap between decriminalization and regulation.
Tennessee lawmakers weigh medical marijuana framework, AOL reports
Tennessee legislators are discussing the structure of a possible medical marijuana program, though public details on a bill, sponsor or vote remain thin.

Idaho Freedom Foundation makes case for HJR 4 drug amendment
The conservative Boise think tank published an Oct. 6 argument for House Joint Resolution 4, a proposed Idaho constitutional amendment on drugs.
More from the newsroom

Survey Names Age Group Most Likely to Drive After Cannabis Use
FOX 9 Minneapolis-St. Paul reported new survey data on which age range drives after cannabis use, putting impaired-driving enforcement back in front of regulators.
Feature Flags Shelf-Life Testing Gap in THC Beverages
A testing expert says a production-day certificate of analysis doesn't guarantee the dose consumers get months later, sharpening the case for shared lab standards.

St. Louis jury awards $10M in Missouri cannabis ownership fight
A St. Louis jury put a $10 million price on a sprawling Missouri cannabis ownership dispute, and the full record is still thin.