Times Square Cannabis Retailer Sues Lender Over Alleged Usury Violation
A New York dispensary claims its financing partner charged interest rates exceeding state caps, spotlighting predatory lending risks in cannabis capital markets.
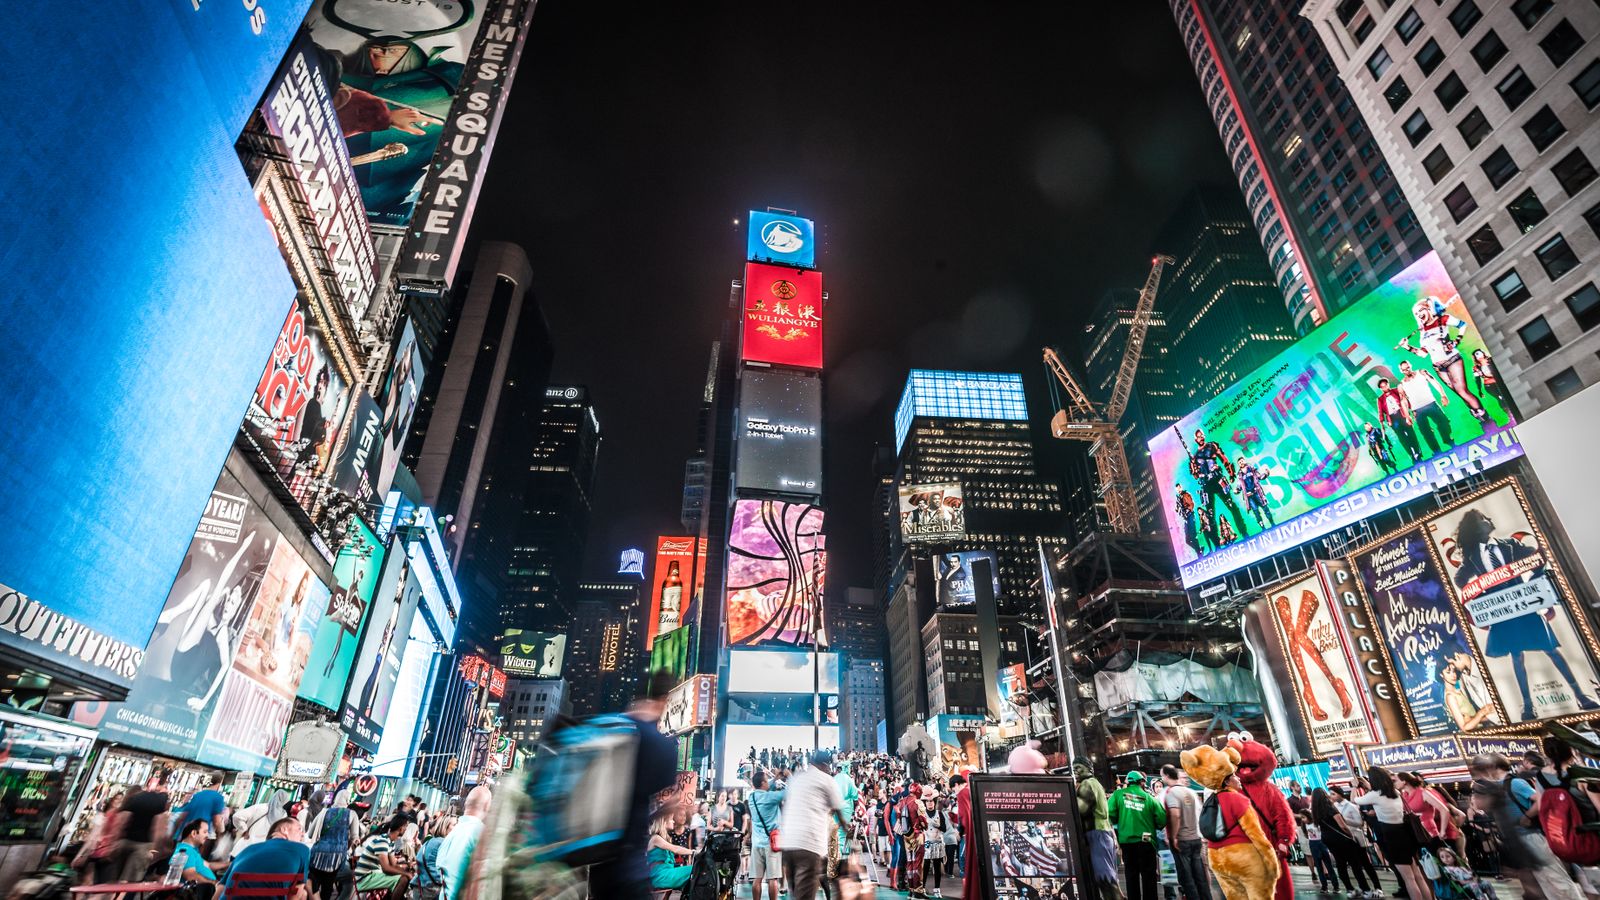
Times Square illuminated at night with bustling crowds and bright billboards in New York City.
The Complaint: Interest Rates Allegedly Exceeded State Criminal Usury Threshold
The dispensary alleges its lender structured a loan carrying an effective annual percentage rate above 16%, the threshold at which New York Penal Law § 190.40 classifies interest charges as criminal usury. The loan agreement included compounding fees, origination charges, and penalty clauses that pushed the true cost of capital well beyond statutory limits, according to the filing. New York's civil usury cap sits at 16% for most commercial loans. Anything above that rate can trigger both criminal liability and automatic contract voidance under state law.
The plaintiff operates under a Conditional Adult-Use Retail Dispensary (CAURD) license issued by the New York Office of Cannabis Management. It secured the financing in early 2025 to cover buildout costs and initial inventory. The retailer claims it had no alternative: federally chartered banks remain unwilling to service cannabis accounts, and state-chartered credit unions have limited appetite for cultivation or retail risk.
The lender, a private equity-backed specialty finance firm, hasn't yet filed a response. Its standard loan products advertise rates between 12% and 18%, with the higher end reserved for operators in nascent markets or those lacking collateral beyond their OCM license.
New York's Usury Framework and Its Application to Cannabis Debt
New York maintains one of the strictest usury regimes in the United States, with a 16% civil cap under General Obligations Law § 5-501 and a criminal threshold at the same rate under Penal Law § 190.40. Contracts that exceed the civil cap are voidable at the borrower's election. Those crossing the criminal line can subject lenders to felony prosecution and automatic forfeiture of principal and interest.
Cannabis operators face a structural bind. Section 280E of the Internal Revenue Code bars federal tax deductions for businesses trafficking Schedule I substances, compressing margins. State banking regulators have issued guidance permitting credit unions to serve licensed operators, but fewer than a dozen New York-chartered institutions have opted in. Private debt funds, merchant cash advance providers, and hard-money lenders dominate the capital landscape, and many charge effective rates between 18% and 36% when all fees and covenants are factored in.
The plaintiff's legal theory hinges on piercing the loan's stated interest rate to calculate its all-in cost. New York courts apply a "totality of charges" test when assessing usury claims, aggregating origination fees, servicing charges, equity kickers, and prepayment penalties into a single APR calculation. If that composite rate exceeds 16%, the contract is void ab initio regardless of how the lender labeled individual line items.
For context on New York's broader cannabis financing landscape, see the CannIntel topic hub on New York cannabis financing.
Implications for Cannabis Capital Markets and Operator Risk
If the plaintiff prevails, the ruling could void hundreds of similar loan agreements across New York's licensed cannabis sector and expose lenders to clawback liability for previously paid interest. At least a dozen specialty finance firms have originated cannabis-secured loans in New York since the CAURD program launched in late 2022. Many carry stated rates near the 16% line. Additional fees may push the effective rate into usurious territory under the totality-of-charges doctrine.
The case also underscores the distortions created by federal prohibition. Cannabis operators can't access Chapter 11 bankruptcy protection due to the Controlled Substances Act, leaving them with limited leverage when negotiating debt restructurings. Lenders, in turn, price that illiquidity into their underwriting, compressing the window between viable commercial rates and usury violations.
New York's Department of Financial Services has the statutory authority to charter a state-owned cannabis banking entity. No such institution exists. Governor Kathy Hochul's 2025 budget proposal included seed funding for a public cannabis credit facility, but the legislature stripped that provision in final negotiations. Without a public option, operators remain dependent on private lenders operating in a gray zone between compliant pricing and predatory extraction.
The next signal to watch: whether the New York Attorney General's office opens a parallel investigation into the lender's practices. AG Letitia James has previously intervened in usury cases involving small-business lending, and her office has statutory authority to seek restitution on behalf of affected borrowers. A coordinated enforcement action could accelerate settlement discussions and force industrywide repricing of cannabis debt.
Sources
The cannabis newsletter you forward to your team.
Federal policy, market data, grower alerts, and the one story that matters today. Sent every weekday at 7am. Free.
No spam. Unsubscribe with one click. 21+ only.
Related from Business

Organigram enters fight for Aurora as Curaleaf bid clock runs
British American Tobacco's stake in Organigram could put the tobacco giant at the center of the Aurora contest before Curaleaf's offer expires Dec. 4.
Tilray Medical Wins Approval for In-House EU-GMP Cannabis Testing
Tilray Medical can now run EU-GMP quality testing in-house, a move that could shift lab costs and batch-release timing, though key details remain undisclosed.
Canopy Growth Secures EU-GMP Certification at Smiths Falls
Canopy Growth's Smiths Falls site is now certified for softgel manufacturing and primary packaging of softgels, oral liquids and dried flower, extending its EU-GMP supply chain.
More from the newsroom
Nevada County Approves Dispensary Selection Process for Two Towns
Supervisors approved a process for choosing cannabis dispensary operators in North San Juan and Soda Springs, but the county notice leaves key details unstated.
DEA Accepts New Report in Rescheduling Hearing; Foes Seek Discovery
DEA does not object to a new report entering the marijuana rescheduling record, while opponents ask for added testimony and document discovery.
Puerto Rico Rolls Back Medical Cannabis Workplace Protections
High Times Magazine reports Puerto Rico has narrowed employment protections for medical cannabis patients, raising questions about which workers lose coverage and which keep it.