Tilray Posts Record Revenue and Net Cash as Mix Shifts
Kalkine Media's read on Tilray's latest results points to record revenue and a net cash position, with the company's mix of businesses doing more of the work.
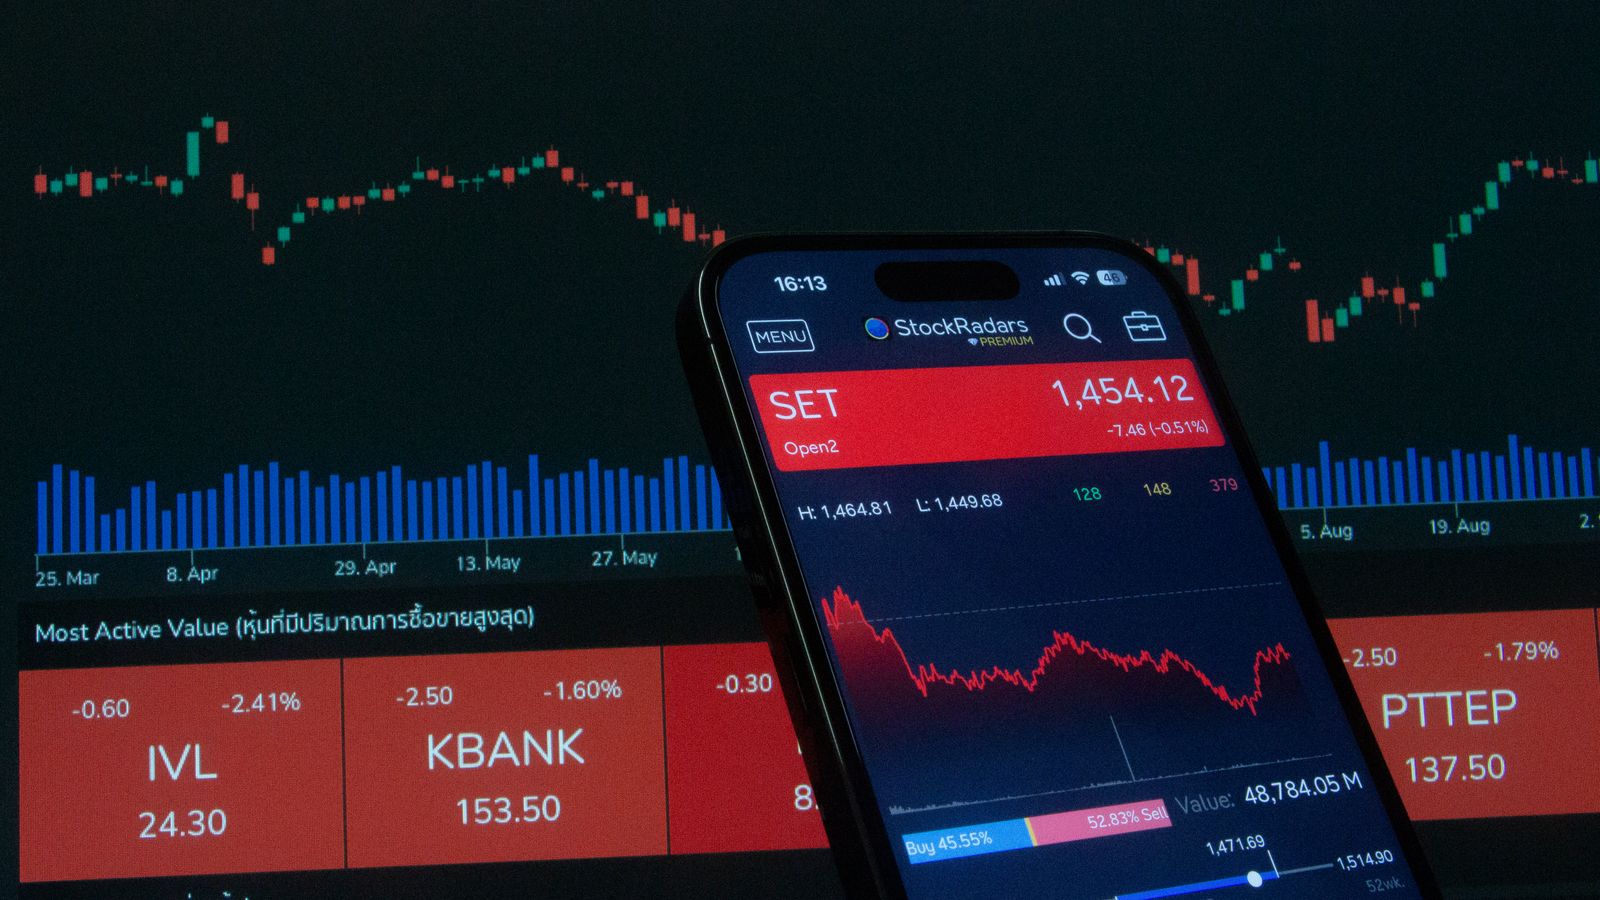
Mobile app showing stock market data with charts on screen.
Tilray's latest results center on record revenue and net cash
Kalkine Media's November 19 analysis highlights record revenue and a net cash position as the two headline figures from Tilray's most recent report.
It's a headline-level summary, and the source payload doesn't carry the underlying dollar figures. We aren't going to guess at them. Readers who need exact revenue, margin and cash numbers should go to Tilray's filing with the SEC, linked below.
What the framing does tell us is where the story sits. Record top line plus net cash is the combination analysts have wanted from a company that spent years burning cash through the post-2019 cannabis downturn.
The 'broader business mix' is the real story
Kalkine's emphasis on Tilray's broader business mix points to diversification beyond adult-use cannabis as the engine behind the record result.
Tilray has long described itself as a multi-segment operator. Its portfolio spans cannabis, beverage alcohol, wellness and distribution. The pitch to investors: no single regulatory regime can sink the whole business.
That's a product-portfolio argument as much as a financial one. Think of a SaaS vendor that sells a core platform plus payments and add-on modules, where the blended revenue runs steadier than any one line.
Why net cash matters more than the revenue headline
A net cash position means Tilray holds more cash than debt, which changes how the market prices its risk.
Revenue records are easy to find in a sector built on acquisitions. Net cash is harder. It gives management room to fund operations, pursue deals or return capital without leaning on dilutive raises or expensive convertible notes.
Balance-sheet strength has become the dividing line for cannabis operators in general. Companies that can't access conventional banking or that bear 280E tax drag need that cushion. Tilray, a Nasdaq-listed company with Canadian roots, has more financing options than most U.S. plant-touching peers, and net cash makes those options cheaper.
What the mix means for operators and vendors
A diversified Tilray changes how suppliers, retailers and software vendors should size the company as a counterparty.
A producer with beverage and wellness revenue behind it can absorb cannabis price compression better than a single-category licensed producer. Wholesale partners and distributors should read that as lower counterparty risk.
Tech procurement shifts too. Multi-segment operators tend to buy enterprise-grade ERP, inventory and compliance tooling across business lines instead of a single seed-to-sale stack. That favors vendors who integrate with general-ledger and supply chain systems, not only with state track-and-trace APIs.
The investor read: strength with caveats
Record revenue and net cash are real positives, but the headline alone doesn't show profitability or cash flow quality.
Revenue growth in cannabis has often been bought through M&A. Net cash can reflect asset sales or financing timing rather than operating strength. Neither shows up in a headline summary.
That's the gap in this signal. Before treating the print as a turning point, investors should check three things in the filing: operating cash flow, gross margin by segment, and how much of the growth was organic versus acquired.
For deeper context on prior quarters and the company's trajectory, see the CannIntel topic hub on Tilray Brands earnings.
Regulatory backdrop keeps the stakes high
Tilray's mix is partly a hedge against U.S. federal uncertainty, where rescheduling and 280E relief remain unresolved variables.
Any move by the DEA to shift marijuana to Schedule III would reshape tax treatment for U.S. operators under 280E and could widen the field of competitors for Tilray's cannabis lines. Tilray's diversified model blunts the downside if that process stalls and cushions the upside if it doesn't.
Meanwhile, Canada's market remains price-competitive and Germany's evolving framework offers European exposure. Tilray's footprint across those jurisdictions is part of why analysts treat it differently from MSOs focused on states like California or Ohio.
The next hard signal is the full earnings filing and call transcript. Watch segment-level margins and the cash flow statement. Those two lines will tell you whether this record is durable or just one good print.
Sources
The cannabis newsletter you forward to your team.
Federal policy, market data, grower alerts, and the one story that matters today. Sent every weekday at 7am. Free.
No spam. Unsubscribe with one click. 21+ only.
Related from Business
Seeking Alpha Flags Texas Politics as a Potential Verano Tailwind
A Seeking Alpha piece argues a shifting Texas political landscape could benefit Verano Holdings (OTCMKTS: VRNO), but the underlying thesis is thin on published specifics.

IM Cannabis Files 3:1 Share Consolidation to Defend Nasdaq Listing
The Israel-focused cannabis operator will fold every three common shares into one, a reverse-split move aimed at keeping its U.S. exchange listing alive.

Licensed Cannabis Event Sales Hinge on State Rules, Logistics
MGRetailer's comparison of state event rules, plus Minnesota's Legacy Cup handling $60,000 in orders, shows licensed event sales are an operations game, not a booth game.
More from the newsroom

Senate Panel Keeps DC Sales Rider, Backs Drug Testing Language
A Senate appropriations panel moved to maintain the ban on DC marijuana sales while urging federal agencies to preserve cannabis drug testing if rescheduling proceeds.

Hemp Fight Could Derail Federal Funding Bill, Marijuana Moment Reports
A Marijuana Moment newsletter flags the hemp debate as a threat to must-pass federal funding legislation, but the underlying provisions were not available for review.
Pennsylvania Democrats Hold Harrisburg, but Adult-Use Cannabis Still Stalled
With Democrats holding the governor's office and the House, Pennsylvania's path to adult-use legalization still runs through a Republican Senate and unresolved structural disputes.